

Following my earlier CoreWeave deep dive, I wanted to re-visit the investment case after the recent sell-off.

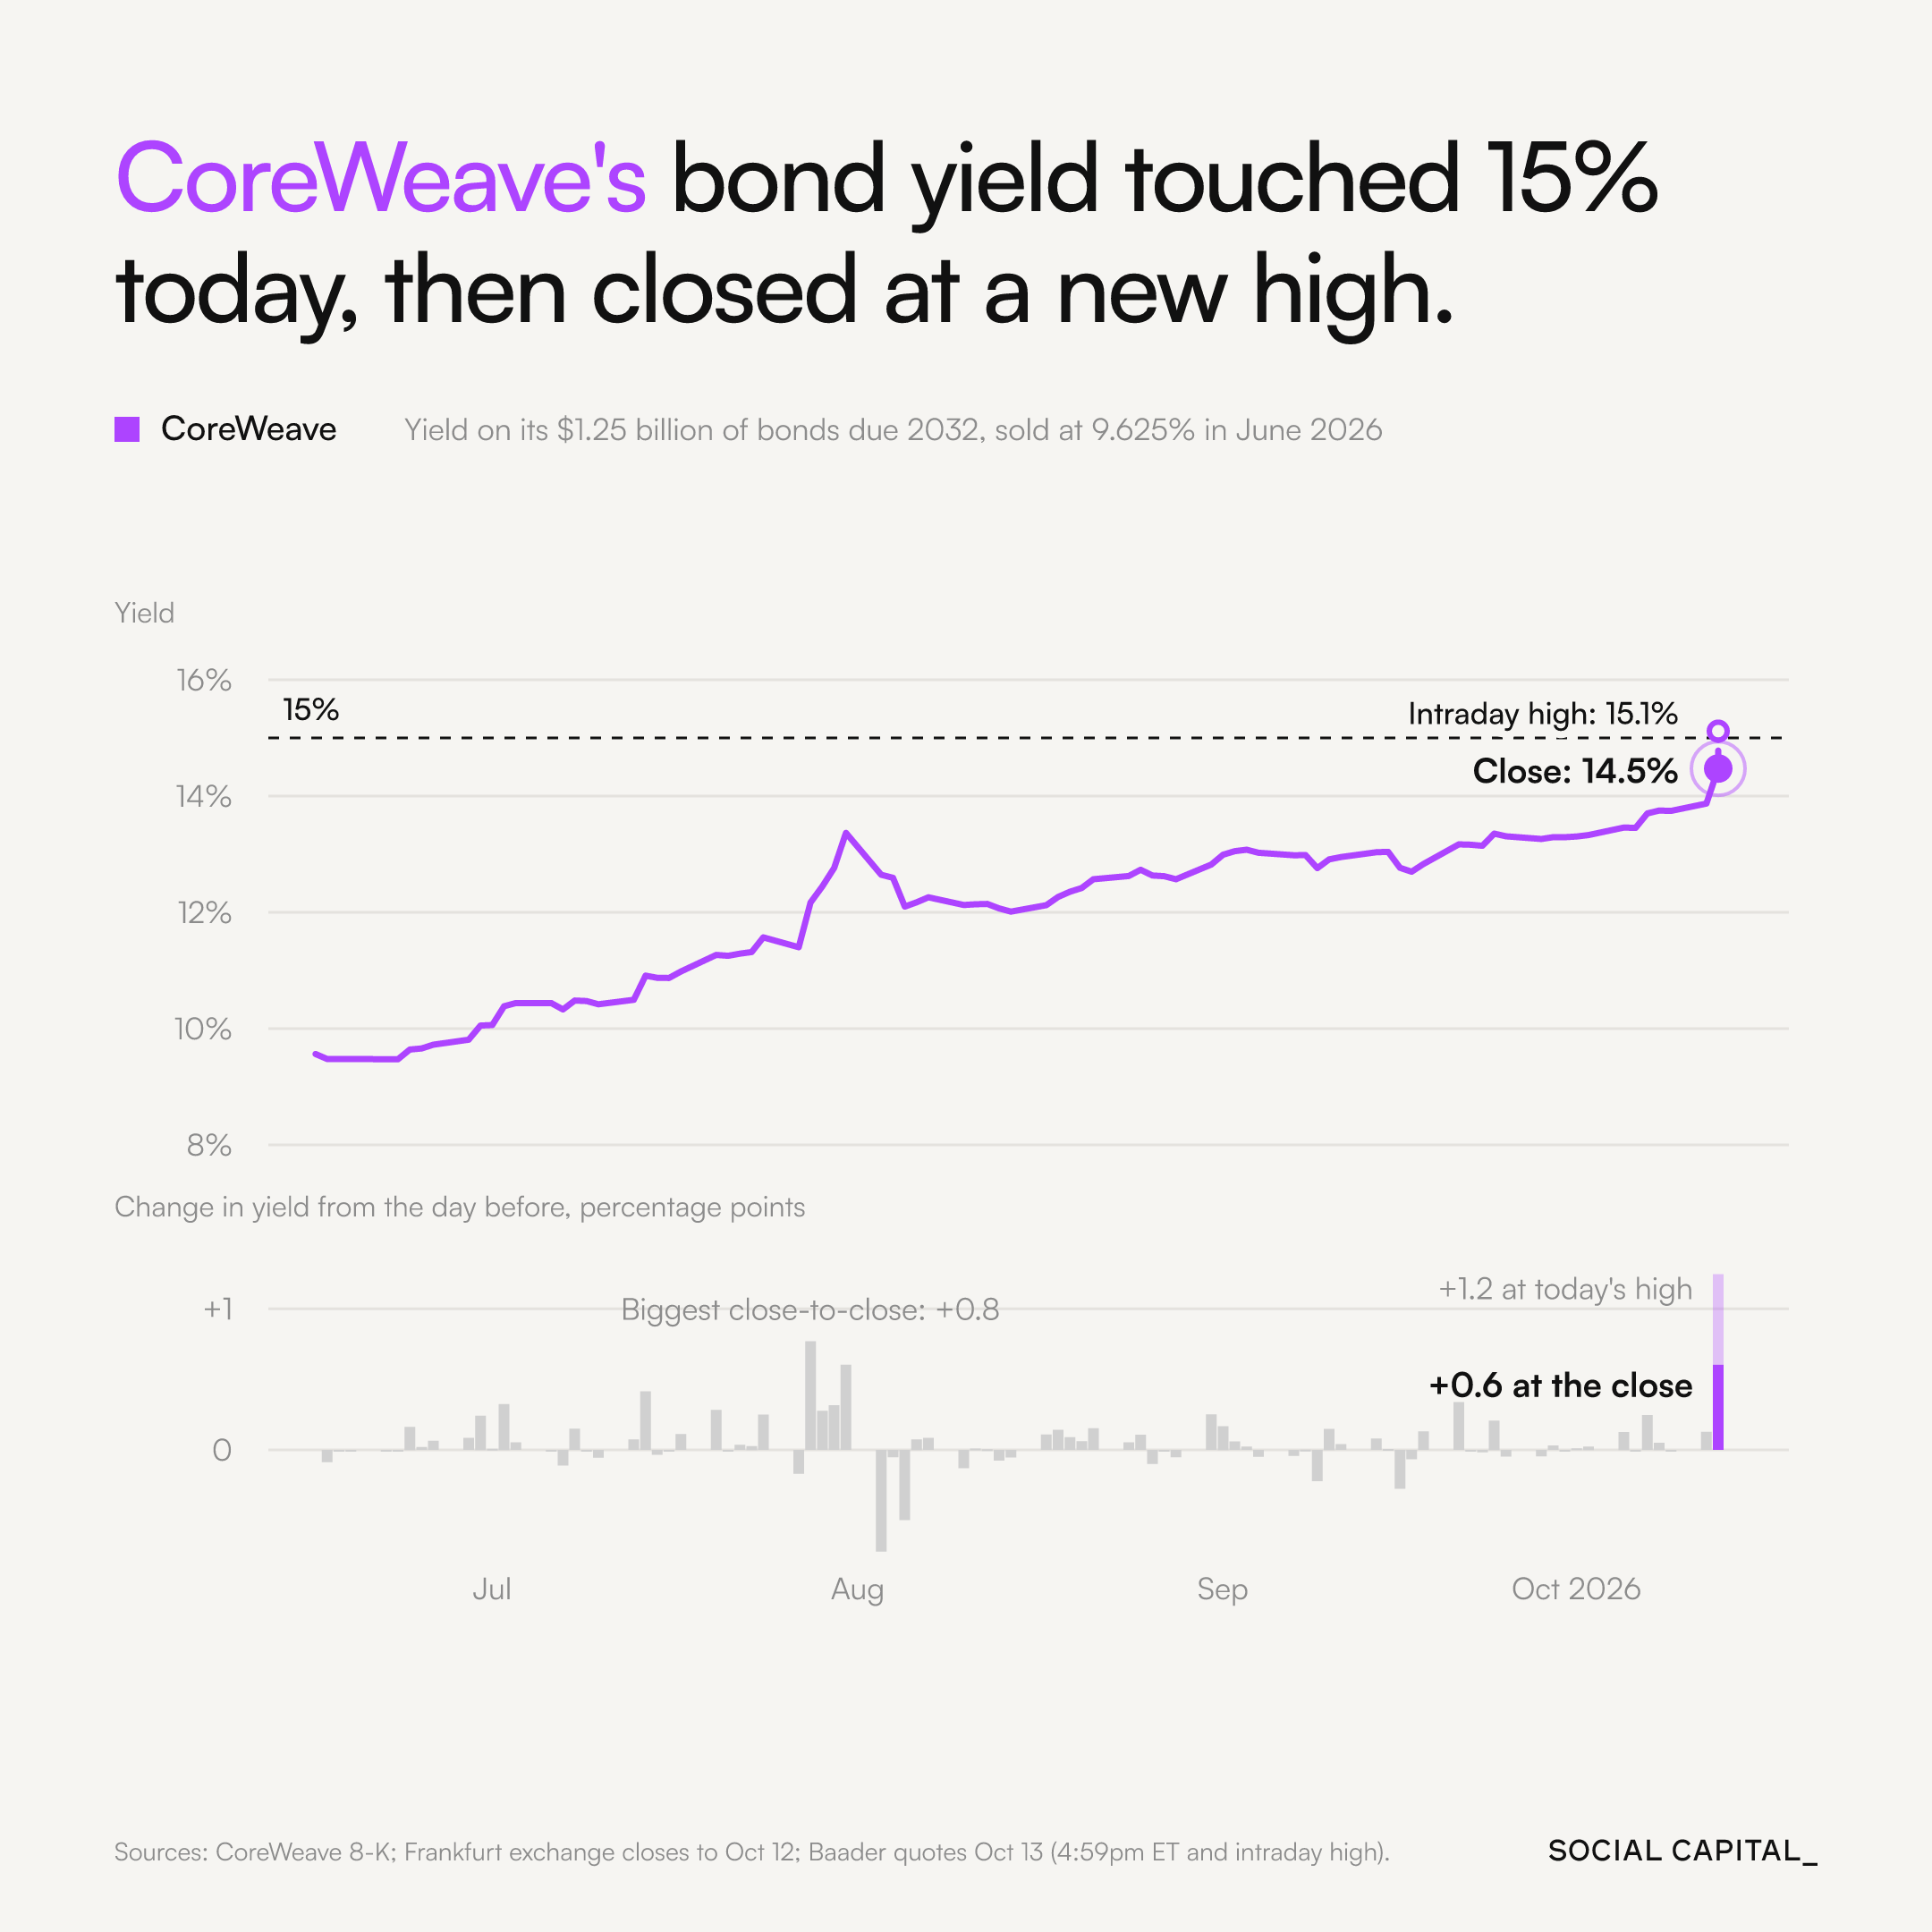
In the past week, CoreWeave bonds sold off, with yields touching 15% amidst higher than expected inflation and recent news around the 2 massive AI giants: OpenAI and Anthropic.
On 8th October, the FT reported annualised revenue approaching $50 billion, versus the approximately $70 billion previously communicated. It turned out to be a gap in how revenue was calculated, but it was enough to show the fears among investors.
On 14th October, Anthropic reported Q3 revenue of $16.8 billion, up 45% QoQ. This remained exceptional growth, but represented a slowdown from the previous quarter and disappointed some investors’ expectations.
With these 2 labs being the harbinger for all other AI companies, the connection was great to CoreWeave, with its future revenue entirely dependent on the capability of these businesses to fulfil their contracted capacity.
For a business that relies heavily on external financing to build infrastructure, the 15% bond yields are hugely important. Higher funding costs can weaken project returns and make future growth more expensive.
Yet, the operating picture remains encouraging. CoreWeave continues to hold a substantial contracted backlog, while SemiAnalysis’s latest assessment supports its technical credentials. The tension is between strong demand for its infrastructure and growing concern about how that infrastructure is financed.
Below, I discuss the pros/cons of owning CoreWeave at these prices amidst recent happenings:
