

Revenue: $8.58B v $8.05B est. (+43.4% YoY)
EPS: $0.78 v $0.81 est.
Sea Limited reported earnings on 10th November before the market open.
The stock opened in pre-market down 10%, was up as much as 9% during market hours and ultimately closed the day down 1.5%.
Selected Key Metrics
Total Gross Profit: $3.94B (+51.4% YoY)
Operating Income: $664.2M (+39.5% YoY)
Total Net Income: $502.5M (+34.0% YoY)
Total Adjusted EBITDA: $931.3M (+28.9% YoY)
Provision for Credit Losses: $681.5M (+82.3% YoY)
GAAP Diluted EPS: $0.78 (vs $0.59 in Q3 2025)
Gross Cash: $9.5B (down from $10.3B in Q2 2026)
E-Commerce (Shopee)
Gross Orders: 4.5B (+25.5% YoY)
GMV: $39.7B (+23.3% YoY, ~26.5% ex-FX)
Revenue: $6.1B (+41.3% YoY)
Adjusted EBITDA: $269.2M (+44.7% YoY)
Digital Financial Services (Monee)
Consumer & SME Loans Outstanding: $12.6B (+60.0% YoY)
Revenue: $1.6B (+63.9% YoY)
Adjusted EBITDA: $298.3M (+15.5% YoY)
90-Day NPL Ratio: 1.3% (up from 1.0% in prior Q)
Digital Entertainment (Garena)
Bookings: $890.0M (+5.9% YoY)
Revenue: $840.1M (+28.6% YoY)
Adjusted EBITDA: $458.2M (+45.9% YoY), 51.5% of bookings
Quarterly Active Users: 671.7M (flat YoY)
Quarterly Paying Users: 68.6M (+4.1% YoY)
Paying User Ratio: 10.2% (vs 9.8% in Q3 2025)
Average Bookings Per User: $1.33 (vs $1.25)
Share Repurchase Program
Repurchased 11.1M shares for $997.2M in total, or ~$89.84 per share. Since the Q2 update, 6.4M shares for ~$580M, or ~$90.66 per share
The board also authorised a new $1B share buyback program on 9th November with no expiry.
This was yet another record quarter for Sea. Revenue of $8.6B, all-time highs in Shopee GMV and EBITDA, and a Monee loan book above $12B.
However, it was not a fantastic quarter for the business. Under the headlines, almost all of Shopee’s monetisation gains went straight back into marketing, Monee is buying growth with marketing and provisions, CAPEX has roughly doubled and there are concerns to be had with GMV growth.
We will discuss the quarter in detail below.
Table of Contents
Shopee (E-Commerce)
Monee (Digital Financial Services)
Garena (Digital Entertainment)
Management Commentary
Concluding Thoughts
1. Shopee (E-Commerce)
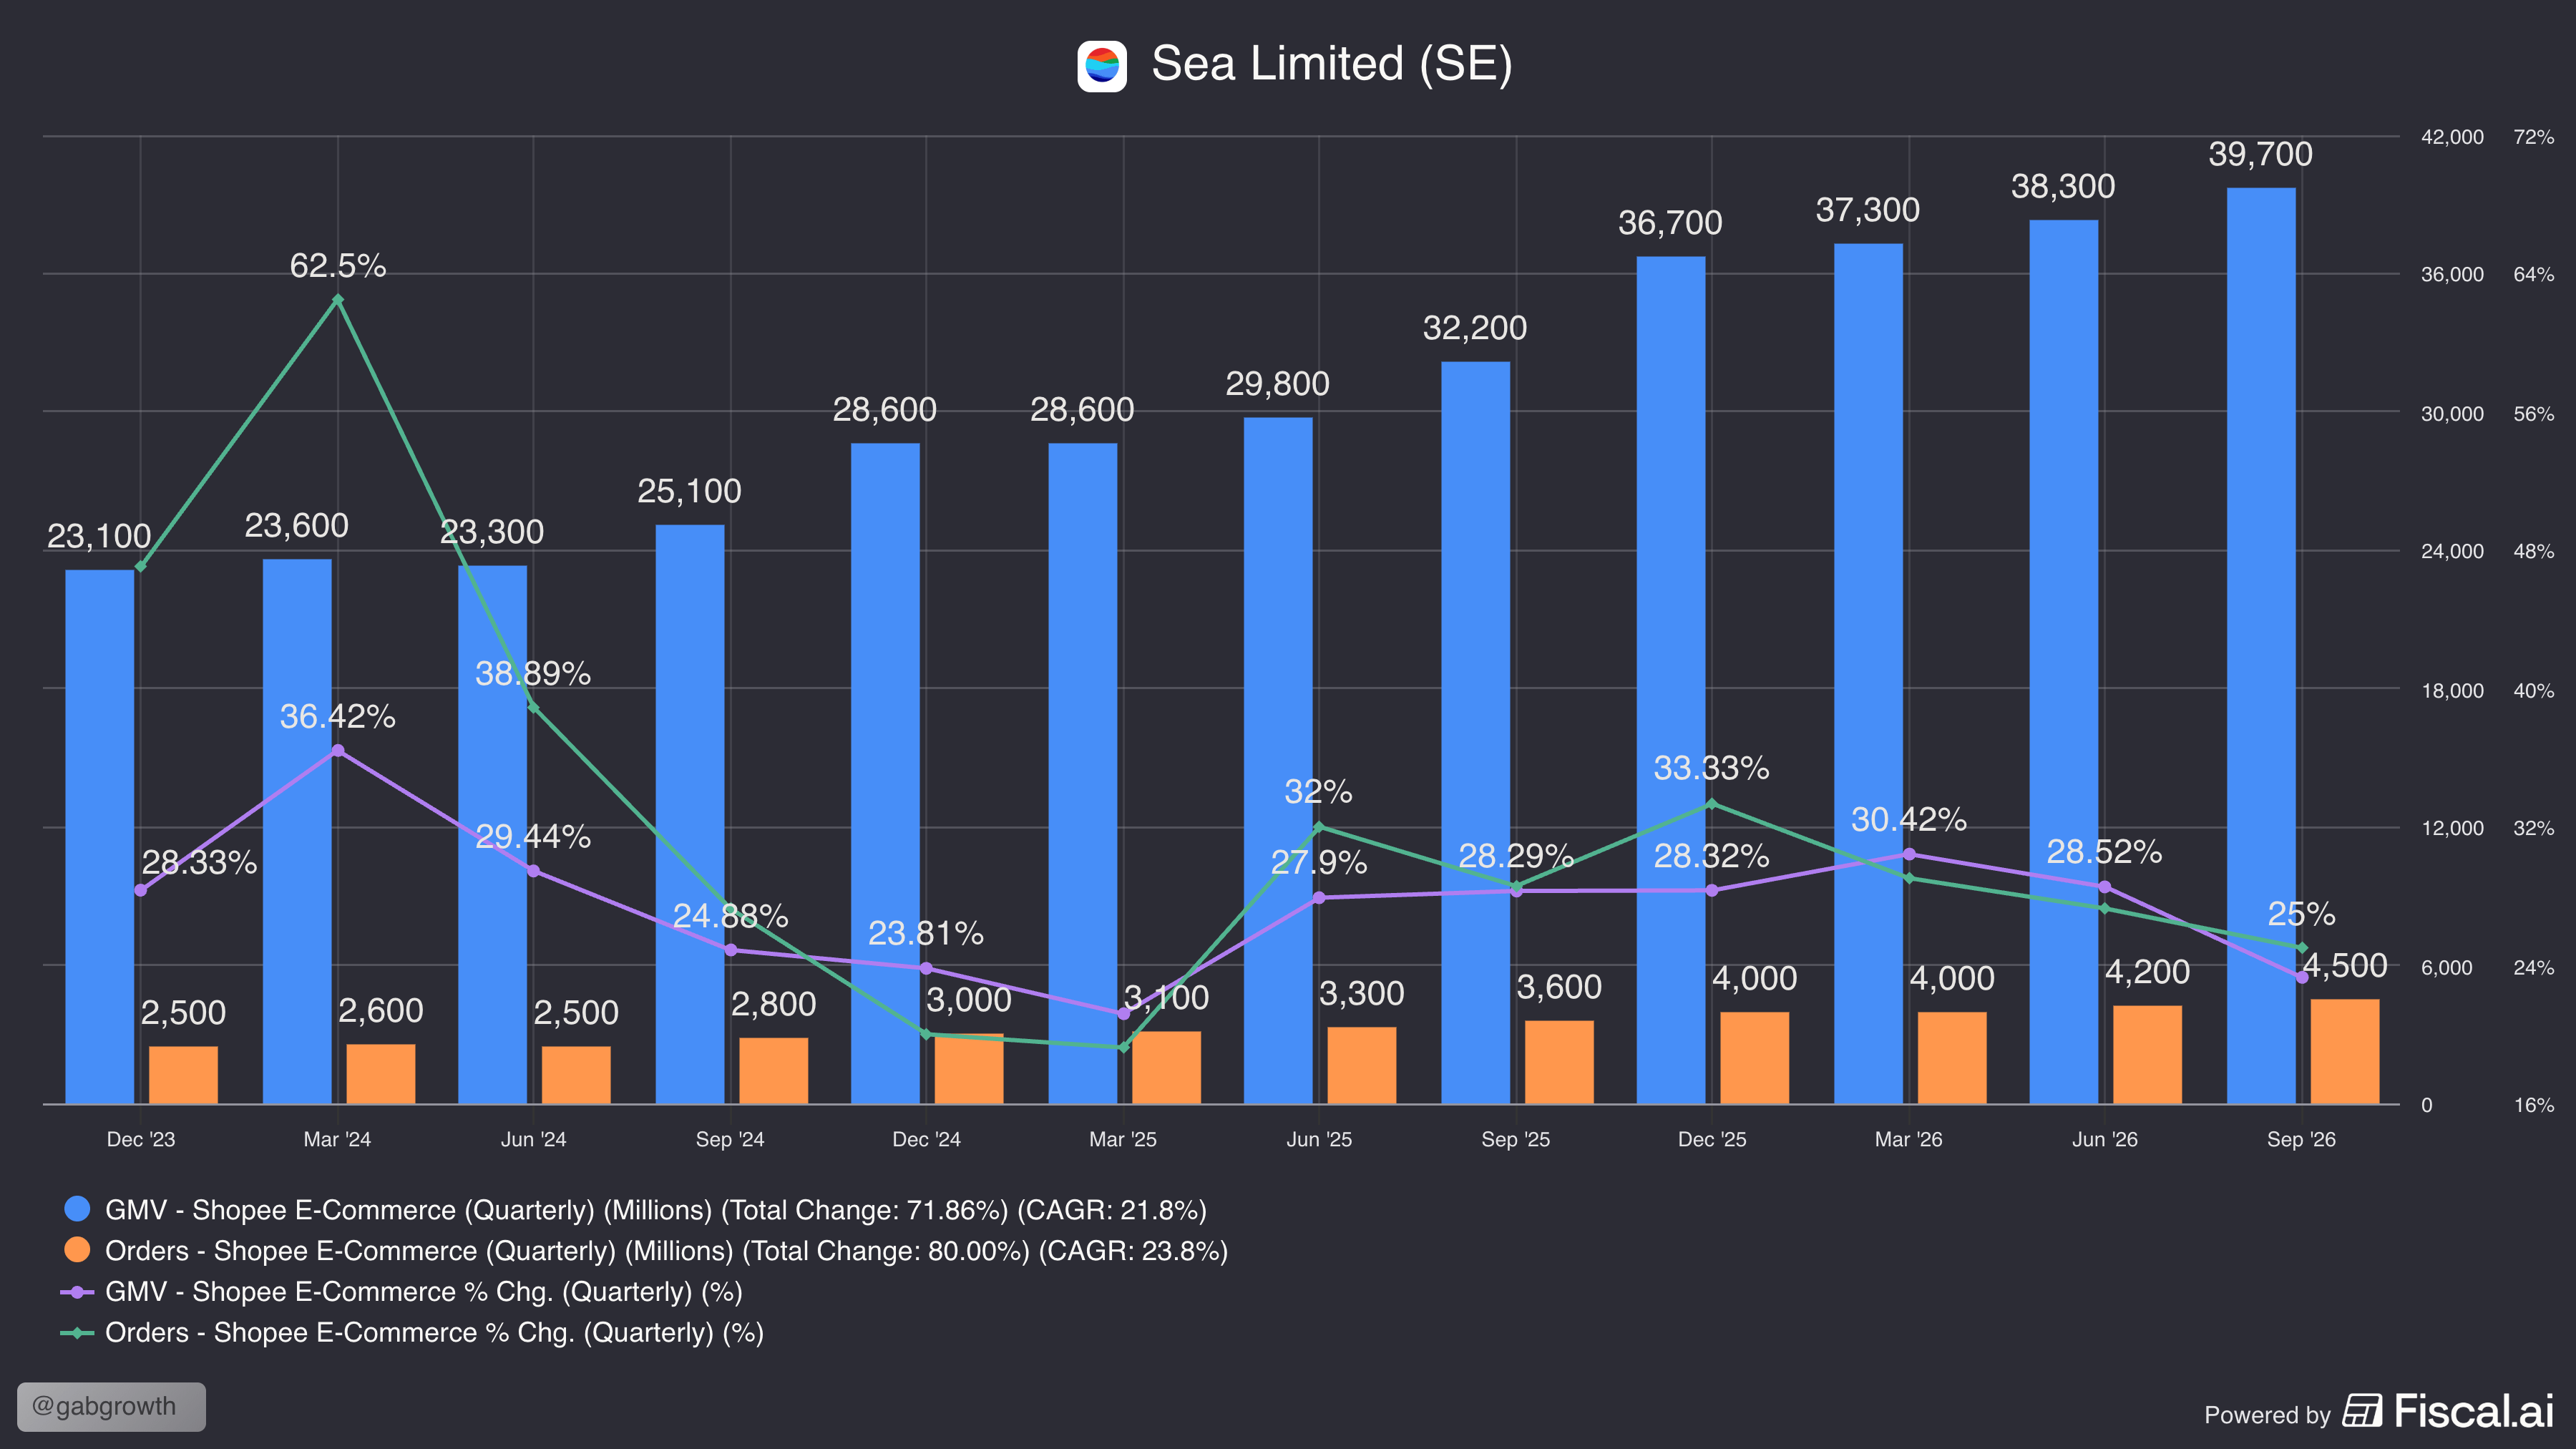
Shopee set another all-time high in GMV and gross orders, its 9th straight quarter of sequential growth. GMV growth slowed to 23.3% from 28.5% in Q2, but most of that was currency. Excluding FX, GMV grew ~26.5%, roughly in-line with last quarter.
Management again reiterated full-year guidance of ~25% GMV growth and $1B in Shopee Adj. EBITDA, and said they are “on track” for both.
Core marketplace revenue (transaction fees and ads) grew 50.6% YoY to $4.6B, still more than double the pace of GMV. It is a deceleration from 65.6% in Q2, which was always likely as the commission increases from last year start to lap.
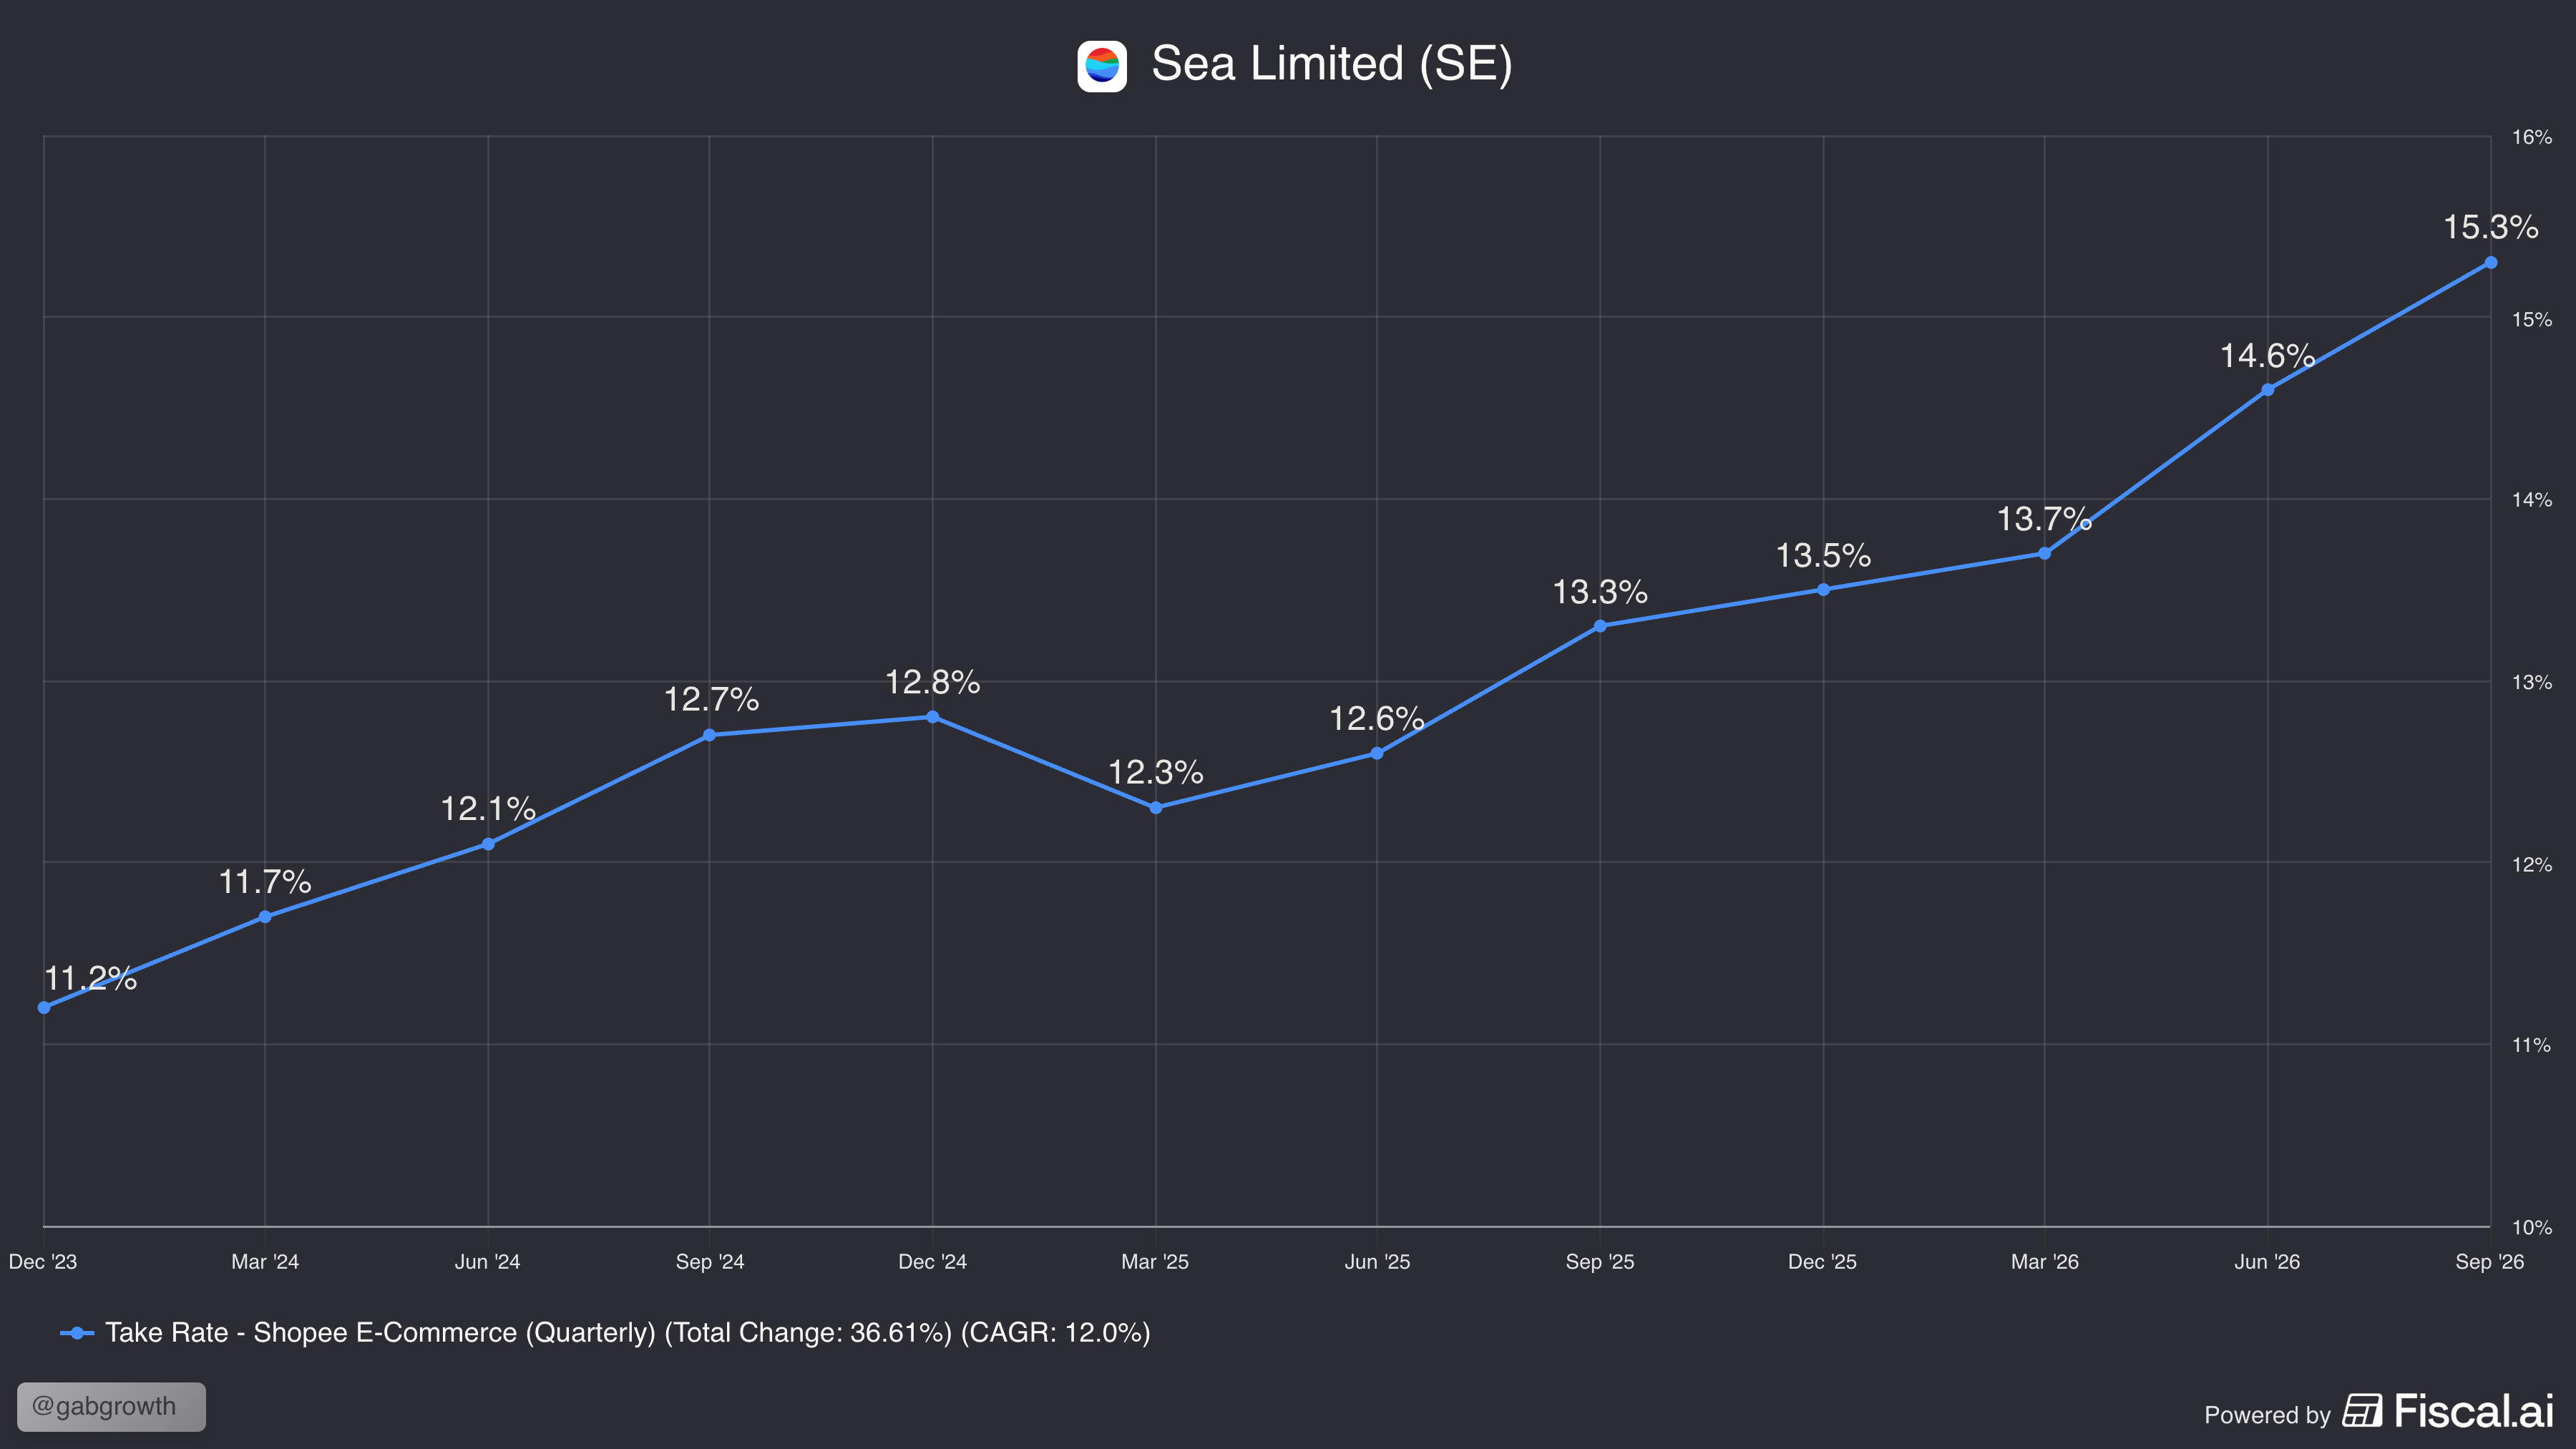
Take rates have continued to climb, reaching 15.3%, up from 14.6% in Q2 and 13.3% a year ago. Core marketplace take rate alone is now 11.6%, up from 9.5% in Q3 2025.
Ads are now a major driver for monetisation. Ad revenue grew more than 55% YoY, ad-paying sellers grew more than 35%, average ad spend per seller rose ~13%, and ad take rate improved by more than 8bps YoY.
Management said future take-rate gains will come mostly from ads and “less from the fixed commission side”. This is definitely the healthier lever, because sellers pay for ads when they get a return, while a commission increase is a tax on sellers.
Profitability
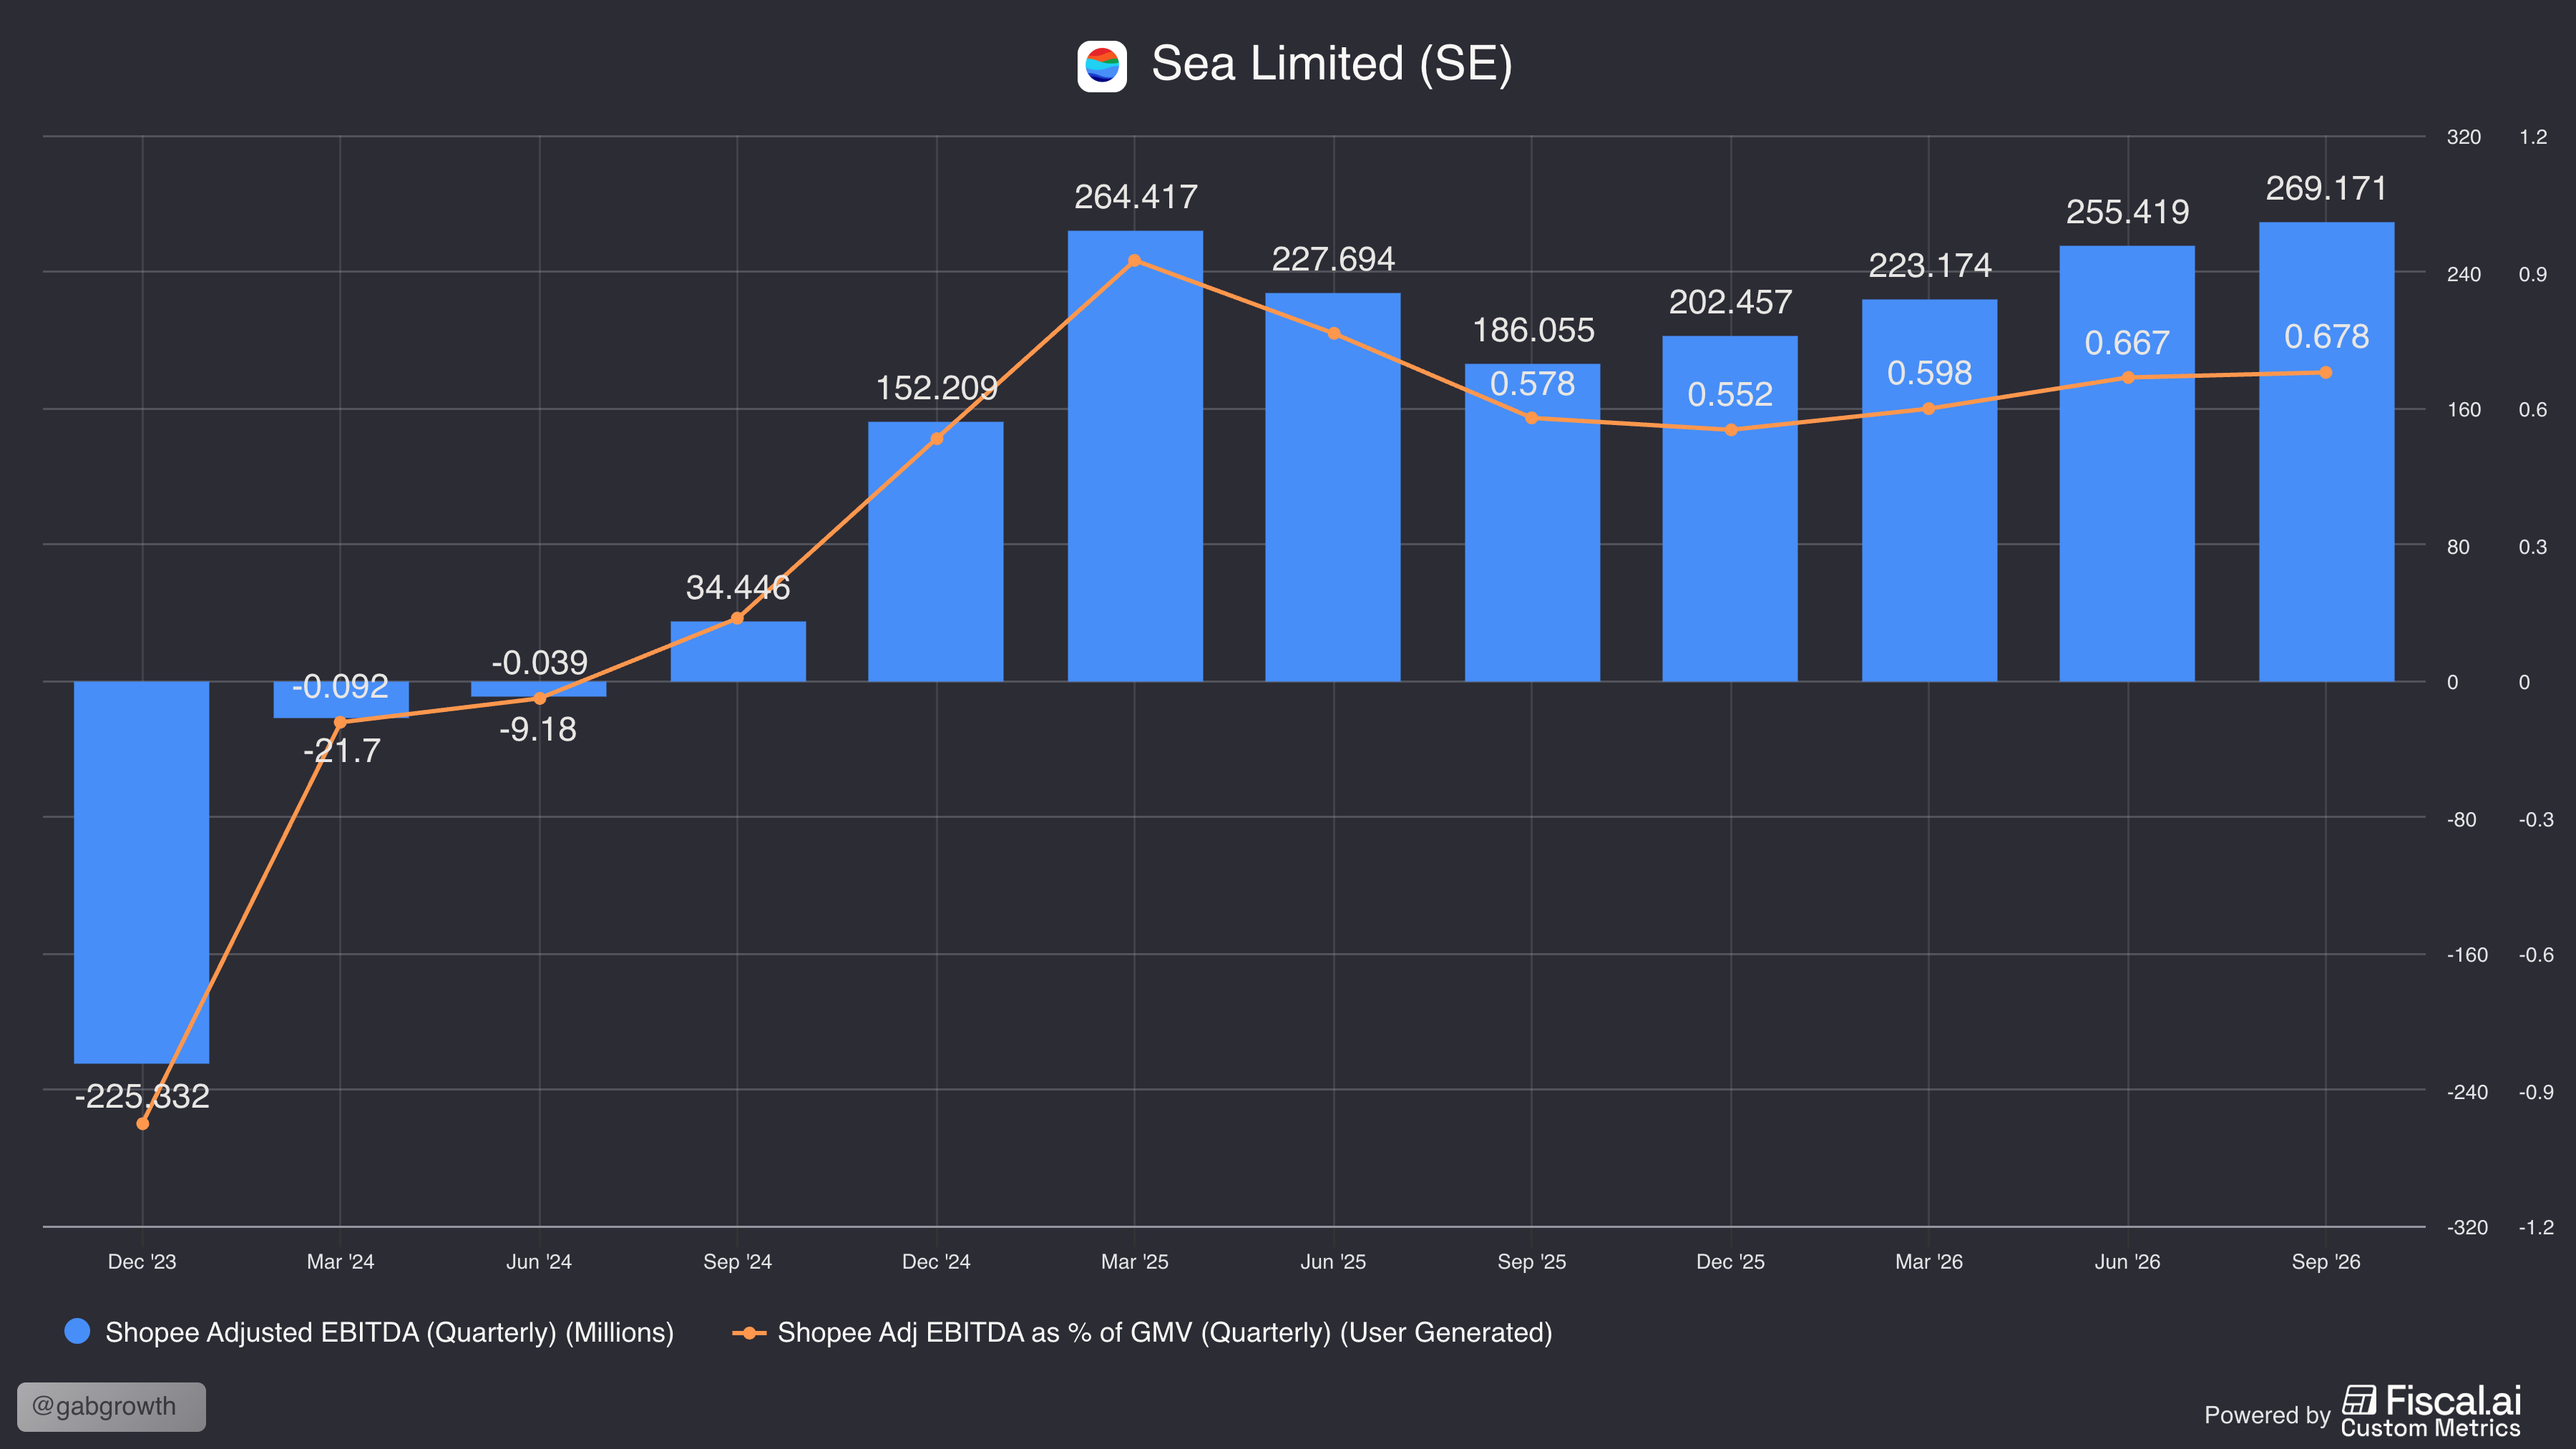
Adj. EBITDA hit a record $269M, +45% YoY, or 0.68% of GMV. This was a 100bps increase from Q3 last year, but about flat sequentially.
This begs the question, which was asked by the MS analyst on the call: where did the monetisation gains go?
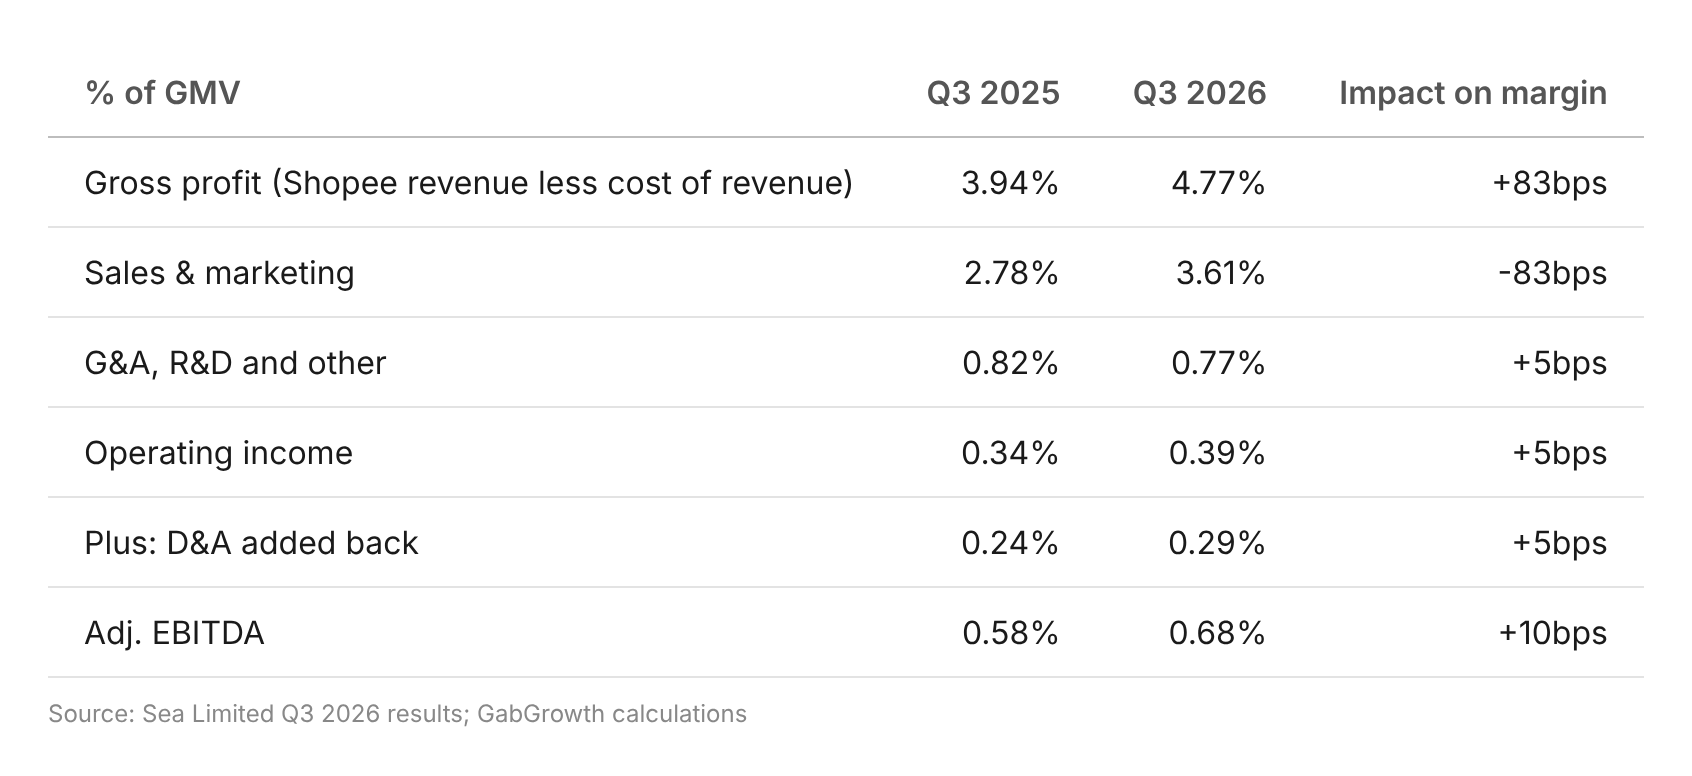
Shopee’s gross profit per dollar of GMV rose 83bps, and almost exactly the same amount went back into sales and marketing, which grew 60% YoY to $1.4B. The 10bps EBITDA margin gain came from overhead leverage (+5bps) and higher D&A being added back (+5bps).
There is also a second, less visible investment. Value-added services revenue (mostly logistics fees) was flat YoY at $724M while orders grew 25.5%, so logistics revenue per order fell ~20%. This makes sense considering free-shipping thresholds being lowered and the cheap shipping option now making up more than half of Indonesian orders. These subsidies show up as lower revenue and not as marketing spend.
To be clear, this is a deliberate choice by management. Chris Feng said future monetisation gains would be split, with “part of that” flowing to EBITDA and “part of that” going to “the investment to grow our market further”.
Given Q2’s commentary that the path to 2-3% is “relatively straightforward”, I would have liked to see more of the take-rate gain reach the bottom line this quarter. This is one of the disappointing aspects of the quarter for me. I would watch this in Q4.
Another point to note was that Shopee’s D&A grew ~50% YoY to $114M as fulfilment centres and logistics assets come online. On an operating income basis, margin went from 0.34% to 0.39% of GMV, so EBITDA slightly overstates the improvement.
S&M spend increased 60% YoY this quarter while revenue was up only 41% and GMV only 23%. This raised some questions on X including this by Brian Stoffel:
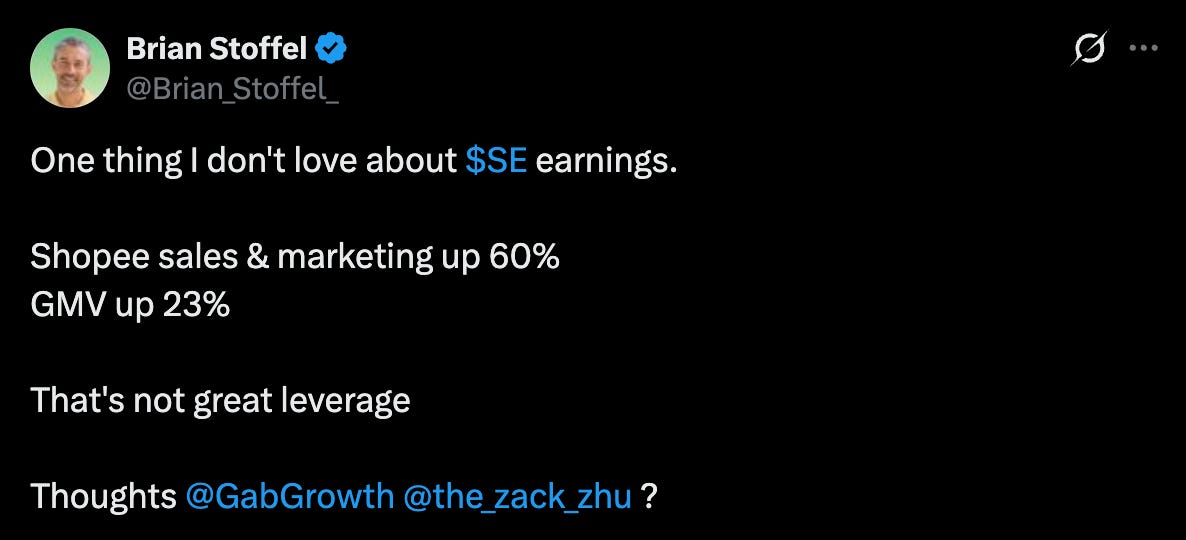
My belief is that this has been driven by investments in ShopeeVIP, which we will discuss right after this, and the content ecosystem. Over the past year, content GMV has grown significantly and I would estimate is at ~$8B per quarter now, up from about ~$5B last year.
The fees paid are typically in the 5-7% range based on the type of affiliate (influencer, KOL etc). This would mean an incremental $180M S&M spend from profit sharing to affiliates alone, amounting to about 1/3 of total incremental S&M spend.
ShopeeVIP is burning about $0.80-$1.65 per subscriber per month according to UBS, so they have likely spent ~$150-$200M in the past 9M alone. I would estimate based on these numbers that these investments have accounted for half, or more of incremental S&M spend.
Many of these investments will only pay off in the long-run, and I do think that with management’s statement that content is now contribution margin positive, we should see S&M as a % of GMV and revenue begin to decline.