

AppLovin reported Q3 2026 Earnings after the market close on 4th Nov 2026.
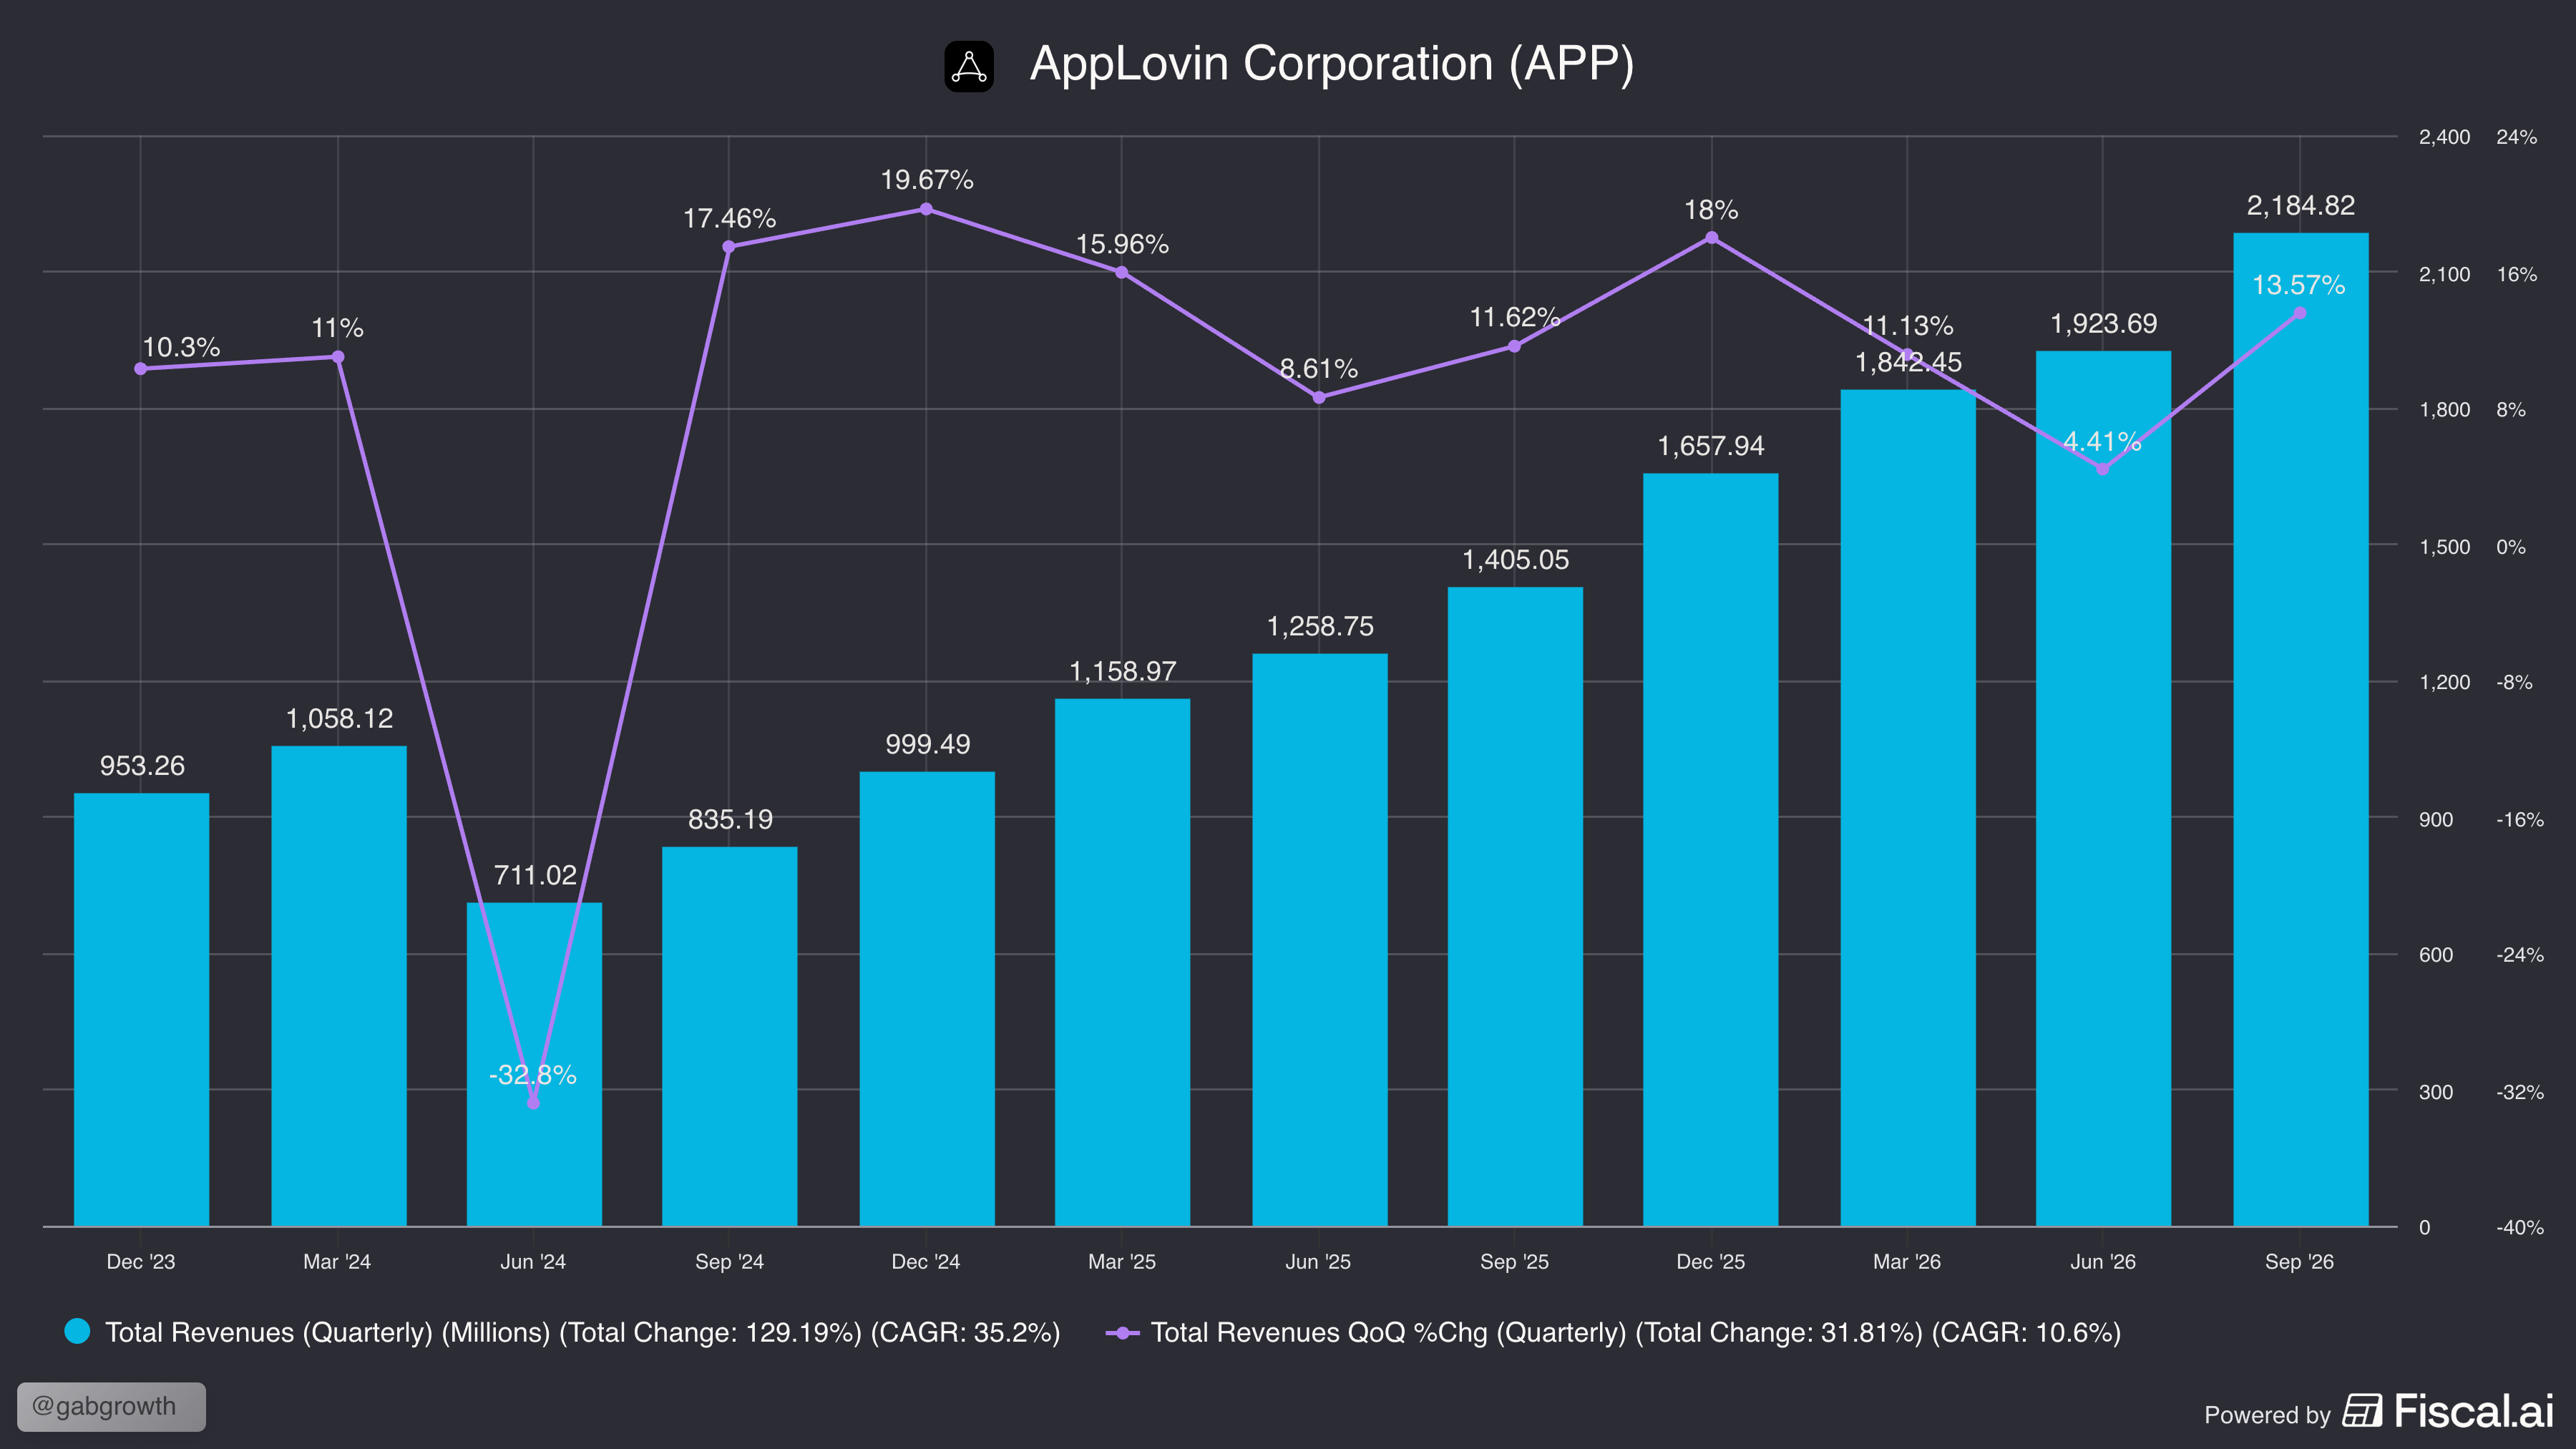
Revenue: $2.185B v $2.08B est. (+55% YoY, +14% QoQ)
Adj. EBITDA: $1.842B (+59% YoY), 84% Margin v 82% same Q last year
Net Income: $1.439B (+72% YoY), 66% Margin
EPS: $4.30 v $4.04 est.
Selected Key Metrics
Gaming Revenue: grew nearly 50% YoY (re-accelerating)
Consumer (e-commerce & non-gaming)
Spend: up triple digits YoY, double digits QoQ
Sequential Revenue Step-Up: +$261M QoQ, the largest in AppLovin’s history
QoQ Flow-Through to Adj. EBITDA: 87%
Free Cash Flow: $1,418M (+35% YoY), 77% of Adj. EBITDA and 65% of revenue
Share Repurchases: 4.1M shares for $1.4B
Shares Outstanding: 331M (~2% lower YoY)
Net Leverage: below 0.1x Adj. EBITDA ($3.17B cash v $3.52B debt)
This was a great quarter for AppLovin. What stood out most to me from these numbers was the sequential step-up. Even the most ardent of AppLovin bulls would admit that Q2 2026 earnings were a disappointment.
Q3 was a significant improvement that allayed many fears for investors. Revenue grew $261M QoQ and beat the top end of guidance by roughly $100M.
Adam Foroughi opened the call by reminding investors that a quarter ago he said the problem was fixed and the business was re-accelerating, and that this quarter is the proof.
According to management, the driver was the partial rollout of AppLovin’s next generation of models, built on the architectural changes Adam first described last quarter. Gaming grew nearly 50% YoY, and he was explicit that the transition is still ahead of them. Adam put the technical complexity on the same level as Axon 2.0, which is the change that made AppLovin what it is today.
Adj. EBITDA grew 59% YoY to $1,842M, beating guidance too, with margin up ~190bps YoY to 84%. Even more impressively, data centre costs fell as a percentage of revenue despite heavier investment in training compute, because the infrastructure team optimised how the models are served.
Net income grew 72% to $1,439M, faster than EBITDA, helped by $86M of other income (largely interest on the growing cash pile) and a lower relative tax drag. Free cash flow rebounded to $1.4B, or 77% of Adj. EBITDA, up from 53% in Q2, when conversion was depressed by the timing of cash tax payments. Management still expects 70-75% conversion for the full year.
Guidance
For Q4 2026, AppLovin guided to $2,365M-$2,395M in revenue (+43%-44% YoY, +8%-10% QoQ) against consensus of ~$2.25B, and $1,995M-$2,025M in Adj. EBITDA at an 84%-85% margin.
At the midpoint, that implies FY2026 revenue and Adj. EBITDA growth of more than 50%. Management also reaffirmed its long-term ambition to compound revenue at roughly 30% a year.
The board increased the buyback authorisation by $3.2B to $3.6B. Since the programme began, AppLovin has repurchased and withheld 104M shares for $9.4B at an average of ~$90, returning 85% of its free cash flow over that period.
In this piece, I will break down the earnings in full, highlight key points on management commentary during the call and discuss my personal thoughts in the last section.